
Title insurance on a $450,000 Texas purchase costs $2,509 for the owner policy under the rate schedule TDI put in force on March 1, 2026, plus $100 for the loan policy issued with it. Real estate title insurance is a one-time indemnity contract: the insurer pays if title is vested differently than Schedule A says, or carries a lien or defect the policy does not except. For a broker or TC, the policy is the easy part. The title insurance commitment is the document you actually have to work.
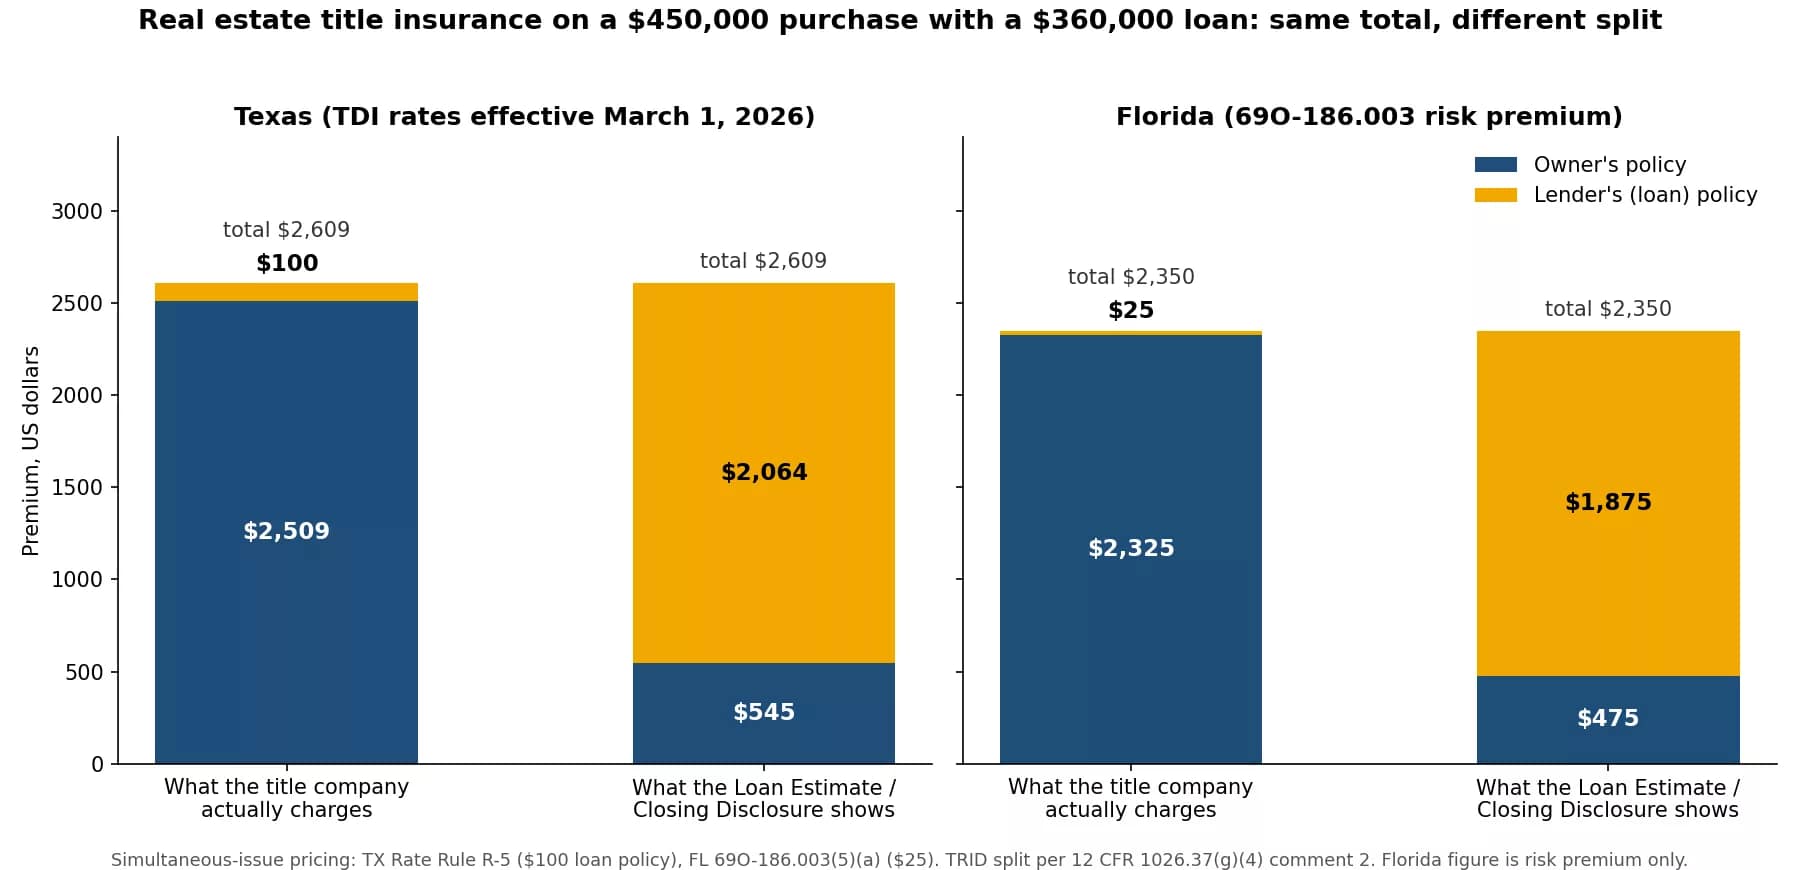
I want to start with the money because the money is where title insurance goes wrong most often, and because this is the year the Texas number changed. Below is the same $450,000 purchase with a $360,000 loan, priced in Texas and Florida, shown two ways: what the title company charges for title insurance, and what the federal Loan Estimate and Closing Disclosure are required to show.
The Texas rate changed on March 1, 2026, and most calculators have not noticed
Texas promulgates title insurance rates. Every title insurance underwriter and every agent charges the same basic premium for the same policy amount, and the Commissioner sets it by order after a public hearing. Commissioner Order 2025-9697, dated December 19, 2025, cut the title insurance basic premium rates by 6.2% effective March 1, 2026. Until that date the rates followed Order 2019-5980, which is the schedule most online calculators and closing cost worksheets were built on.
Try ReBillion Free
Start coordinating transactions like a pro. No credit card required.
The current TDI rate page gives the method for anything over $100,000: subtract $100,000 from the policy amount, multiply by 0.00494, round, add $780. For $450,000 that is $350,000 times 0.00494, which is $1,729, plus $780, which is $2,509. TDI’s own worked example on the same page is $268,500, which comes out to $1,612; I ran that through the same arithmetic and got the same answer, which is the only reason I trust my $2,509.
Under the prior schedule the same policy came to roughly $2,675. I am deriving that from the 6.2% reduction rather than reading it off the old table, so treat it as approximate. The point is that a Texas file quoted in February and closed in April carried a title insurance premium about $165 lower than the estimate made before contract, and if your closing cost estimate template still has the 2019 formula in it, every Texas title insurance quote you give is high.
What an owner title insurance policy actually insures
The form that matters is the ALTA 2021 Owner’s Policy. The Florida Office of Insurance Regulation publishes the Florida-modified version in full, which is useful because the ALTA site itself restricts the forms to licensees. The ten Covered Risks run from the obvious (Risk 1: the Title being vested other than as stated in Schedule A) to the specific (Risk 2.a.iii: a document not properly notarized, including by remote online notarization; Risk 2.a.v: a document executed under a falsified or expired power of attorney; Risk 10: anything recorded between the Date of Policy and the recording of the deed).
Two things in that form change how I would explain title insurance to a client. First, Risk 2.c covers an encroachment or boundary overlap only if an accurate survey would have disclosed it, which is why the survey exception matters so much on the commitment. Second, Condition 8.d says that if the insurer fights a covered claim and loses, the Amount of Insurance goes up by 15%. That is a real feature of the 2021 form and almost nobody mentions it.
The Exclusions are just as instructive. Exclusion 3.a excludes anything the insured created, suffered, assumed, or agreed to. Exclusion 7 excludes any discrepancy in square footage or acreage. Exclusion 6 excludes taxes that become due after the Date of Policy. If a buyer asks whether title insurance covers a zoning violation, the honest answer from the form is: only to the extent of an Enforcement Notice already recorded (Covered Risk 5), and otherwise no (Exclusion 1).
The three-schedule read: how a TC should work a title commitment
The title insurance policy arrives after closing. The commitment arrives before it, and the commitment is a conditional offer of title insurance, not a report. The ALTA 2021 Commitment says so in capital letters on page one: it is an offer to issue a policy, it is not an abstract of title, and the company has no obligation to anyone except the Proposed Insured named in Schedule A. Commitment Condition 2 adds the clock: if all of the Schedule B, Part I Requirements have not been met within the period stated on the form, the commitment terminates and the company’s liability ends.
I read every title insurance commitment the same way, in the same order, and I would build any coordination system to do the same. Call it the three-schedule read.
Schedule A is the identity check. Commitment Date, the policy or policies to be issued, the Proposed Insured, the Proposed Amount of Insurance, the estate being insured, who title is vested in now, and the legal description. Every one of those is a field you compare against the contract. A buyer name that does not match the contract, a policy amount that does not match the sales price, a vesting that names a deceased spouse or an LLC the seller forgot about: those are Schedule A problems and they surface on day one if someone looks.
Schedule B, Part I is the to-do list. The 2021 form seeds it with four standing requirements: notify the company of any party not named who will take an interest or make a loan; pay the purchase price; pay the premium; and record documents, satisfactory to the company, that convey the Title or create the Mortgage. The company then lists the file-specific items by number: payoff of the existing deed of trust, release of a judgment lien, an affidavit of heirship, an entity resolution, a corrective deed. These are the items that stop a closing. Commitment Condition 5.f says the company is not obligated to issue the policy unless all of them are met to its satisfaction. A TC who tracks nothing else about title insurance should track Part I.
Schedule B, Part II is what survives into the policy. Easements, restrictive covenants, mineral reservations, the survey exception, and the gap exception for anything recorded between the Commitment Date and the date the requirements are met. Nothing here needs to be done; it needs to be read against the contract, because the contract decides which exceptions the buyer already agreed to accept and which ones the buyer can object to.
Mapping the read to the Texas contract clocks
The TREC One to Four Family Residential Contract (No. 20-18, 11-04-2024) is the clearest example of how a promulgated contract wires the title insurance commitment into deadlines, so I will use it. Paragraph 6A lists nine categories of permitted exceptions the buyer takes subject to, including restrictive covenants common to the subdivision, utility easements on the plat, and the standard printed survey exception, which 6A(8) lets the parties amend to read “shortages in area” at one side’s expense. Paragraph 6B gives the title company 20 days after receipt of the contract to deliver the title insurance commitment and exception documents, with an automatic extension of up to 15 days or 3 days before closing, whichever is earlier, and a buyer termination right if it still does not arrive. Paragraph 6D runs the objection clock.
| Schedule | What the TC compares it against | TREC 20-18 clock that depends on it |
|---|---|---|
| Schedule A (identity) | Contract parties, sales price, legal description, financing addendum | None directly; mismatches feed every later clock |
| Schedule B, Part I (requirements) | Payoffs, releases, entity documents, affidavits the seller must produce | Closing Date in 9A; Schedule C requirements are never waived by a missed objection |
| Schedule B, Part II (exceptions) | Permitted exceptions 6A(1) through (9); survey | Buyer objection deadline in 6D: the earlier of the Closing Date or the stated number of days after receiving the commitment, exception documents, and survey |
| Revised commitment or new exception document | Whatever changed | 6D restarts the same objection period from delivery of the revision |
| Timely objection by buyer or lender | Seller cure | 15-day Cure Period; buyer then has 5 days after the Cure Period ends to terminate or waive, and silence waives |
The line in 6D that most TCs miss is the carve-out: a buyer who fails to object in time waives the objection, except that the requirements in Schedule C of the commitment are not waived. Texas commitments label requirements as Schedule C rather than Schedule B, Part I, but the function is identical. The contract is telling you that the to-do list never expires. The exceptions do.
One title insurance cost detail worth having in the system: amending the survey exception under 6A(8)(ii) is not free. TDI Rate Rule R-16 prices the amendment at 5% of the basic rate on a residential T-1R policy, with a $20 minimum. On the $450,000 example that is about $125. The contract checkbox decides who pays it, and the Closing Disclosure will show it as an endorsement.
Who pays for title insurance, and the federal line a seller cannot cross
Who pays for the owner title insurance policy is custom and contract, not law. TREC 6A has a checkbox: Seller shall furnish an owner policy at Seller’s or Buyer’s expense. The Florida contracts handle it in their title evidence paragraph. California has no promulgated contract rule at all; it is a line item on the purchase agreement and varies by county.
What is law is RESPA Section 9. 12 U.S.C. 2608(a) says no seller of property that will be purchased with the assistance of a federally related mortgage loan shall require, directly or indirectly, as a condition to selling the property, that title insurance be purchased by the buyer from any particular title company. Subsection (b) sets the penalty: three times all charges made for the title insurance. Regulation X, 12 CFR 1024.16, carries the same prohibition. The statute does not contain a carve-out for sellers who pay the premium themselves; you will see that exception described in industry explainers as HUD guidance, and I could not bind it to the statute or the regulation this run, so I am not asserting it. What I will say is that a listing agent who writes “buyer must use XYZ Title” into a counter on a financed deal has created a treble-damages exposure for the seller, and the TC is often the only person who reads the counter closely enough to catch it.
Why the Loan Estimate shows a number nobody quoted
This is the question I get most from agents reading a Closing Disclosure for the first time in a simultaneous-issue state: the title company quoted title insurance at $2,509 for the owner policy and $100 for the loan policy, and the CD shows the owner policy at $545 and the lender policy at $2,064. Neither number was a mistake.
The CFPB’s TRID title insurance factsheet (June 2020) explains the rule from Comments 37(g)(4)-2 and 38(g)(4)-2. The lender policy is always disclosed at its full, non-simultaneous premium. The owner policy is disclosed as the full owner premium, plus the simultaneous loan premium, minus the full lender premium. In Texas: $2,509 plus $100 minus $2,064 equals $545. In Florida, where Rule 69O-186.003(5)(a) sets the simultaneous loan policy at a minimum of $25: $2,325 plus $25 minus $1,875 equals $475. The totals match the quote exactly. Only the split moves.
The factsheet also covers the case that trips up files where the seller pays: when the contract has the seller paying the full owner premium, the seller credit will exceed the disclosed owner policy cost, and the lender has three permitted ways to show the excess, including a general seller credit in the Summaries of Transactions. The factsheet even confirms that in some states the formula produces a negative owner policy number, and that a negative number is the correct disclosure when the full lender premium exceeds both policies combined. If a client asks you to explain the CD, send them that document. It is nine pages and it settles the argument.
Three title insurance rate regimes, three different answers to “how much”
Title insurance pricing is state law, and the states fall into recognizable groups. Texas promulgates a single schedule by Commissioner order. Florida promulgates a per-thousand title insurance risk premium by administrative rule, and then requires the search, examination, and closing charges to be shown separately at no less than actual cost (69O-186.003(11)(b)), which is why a Florida quote is always larger than the risk premium alone. California files title insurance rates: under Insurance Code 12401.1 every title insurer files its own schedule with the Commissioner, effective no earlier than 30 days after receipt, and under 12401.9 the schedule has to be publicly displayed in every office in the county it applies to. Two California underwriters can and do charge different title insurance premiums for the same policy.
| Policy amount | Texas owner policy (TDI, effective 3/1/2026) | Florida owner policy risk premium (69O-186.003) | California |
|---|---|---|---|
| $300,000 | $1,768 | $1,575 | Filed per insurer; look up the schedule |
| $450,000 | $2,509 | $2,325 | Filed per insurer |
| $600,000 | $3,250 | $3,075 | Filed per insurer |
| $1,000,000 | $5,226 | $5,075 | Filed per insurer |
| Simultaneous loan policy | $100 (Rate Rule R-5) | $25 minimum (69O-186.003(5)(a)) | Filed per insurer |
Florida’s title insurance rule has a second feature worth knowing: reissue rates. Under 69O-186.003(2), if the seller holds an owner policy issued within the last three years and both the agent and the underwriter keep a copy, the new owner policy prices at $3.30 per thousand on the first $100,000 and $3.00 per thousand up to $1 million, instead of $5.75 and $5.00. On the $450,000 example that is $1,380 instead of $2,325. The buyer only gets it if someone asks the seller for the prior policy, which is a document collection task with a dollar value attached, and one I would put on the opening checklist for every Florida resale.
For scale, the industry wrote $5.3 billion in title insurance premiums in the second quarter of 2026, up from $4.5 billion a year earlier, according to ALTA’s market share report published September 22, 2026. The detailed breakdown is behind ALTA’s member login, so I am quoting only the two headline figures.
What I would make the system do
None of the above requires an attorney. It requires someone to read three schedules against a contract on the day the commitment lands, and to keep reading when a revised commitment lands. That is exactly the kind of work that gets skipped when a coordinator is carrying forty files, and exactly the kind of work an AI control plane that orchestrates your stack can carry. ReBillion coordinates your TMS, CRM, signature, and comms, and on title insurance specifically it should do five things.
Pull every Schedule A field and compare it to the contract, then flag the mismatches before anyone else sees the commitment. Turn every Schedule B, Part I requirement into an owned task with the party who has to produce it, and keep those tasks alive regardless of the objection deadline, because the contract says they never waive. Compute the objection deadline from the actual delivery date of the commitment, exception documents, and survey, and recompute it when a revision arrives. Price the title insurance line from the current state schedule rather than a stored estimate, so a Texas file does not carry a 2019 number into a 2026 closing. And read the counter for a seller-mandated title company on any financed deal, because that one sentence is worth three times the premium.
If you want to see how that looks on a live file, book a demo, or look at pricing. For the broader workflow this sits inside, start with what an AI transaction coordinator is and the deadline automation guide. The title insurance clocks interact with the escrow and earnest money clocks, and the premium is one line in the state-by-state closing cost picture. State pages for Texas, Florida, and California cover the rest of each state’s TC requirements, and manufactured home title conversion covers the one case where the “title” in question is a vehicle title rather than a land title. If you are choosing the platform that will hold all of this, the transaction management software guide is the place to start.
Sources, and what I refused to assert
Every title insurance figure above comes from a document I retrieved and read this run: TDI Commissioner Order 2025-9697 and the TDI rate page dated June 5, 2026; TDI Rate Rules R-5 and R-16; Florida Administrative Code 69O-186.003 as published by Cornell LII; the ALTA 2021 Owner’s Policy (Florida modifications) from FLOIR; the ALTA 2021 Commitment redline from ALTA; TREC No. 20-18 (11-04-2024); 12 U.S.C. 2608 from the 2023 U.S. Code at govinfo; 12 CFR 1024.16; the CFPB TRID title insurance factsheet; California Insurance Code Article 5.5; and ALTA’s Q2 2026 market share release.
Things I did not assert because I could not bind them to a primary source: the exact pre-March 2026 Texas premium for any specific amount (derived from the 6.2% cut instead and labelled as such); the “seller pays 100%” exception to RESPA Section 9 (not in the statute or Regulation X text); market share percentages by underwriter (behind ALTA’s login); and any claim about what share of premium is paid out in claims, which is a figure I see quoted constantly and have never seen tied to a current regulator filing. If TREC has issued a revision after 20-18, the paragraph 6 mechanics quoted here are from the 11-04-2024 form and should be re-checked against it.
Frequently asked questions
How much does title insurance cost on a $450,000 home
In Texas, $2,509 for the owner policy under the TDI schedule effective March 1, 2026, plus $100 for a loan policy issued at the same time. In Florida, $2,325 in risk premium for the owner policy under Rule 69O-186.003, plus a $25 minimum for the simultaneous loan policy, with search, examination, and closing charges added separately. In California the premium depends on which insurer you use, because each one files its own rate schedule.
Is the owner title insurance policy required
No. Lenders require a loan title insurance policy on a financed purchase, which protects the lender only. The owner policy is optional for the buyer, which is why the Loan Estimate and Closing Disclosure label it “(optional)” unless the seller is paying for it. Who pays is a contract term; in Texas it is a checkbox in paragraph 6A of the TREC contract.
What is the difference between a title commitment and a title insurance policy
The commitment is a conditional offer to issue a title insurance policy, delivered before closing, and it terminates if the Schedule B, Part I requirements are not met within the period stated on the form. The title insurance policy is the indemnity contract itself, issued after closing and dated at or after recording. The commitment is the document a transaction coordinator works; the policy is the document the buyer keeps.
Can a seller require the buyer to use a specific title company
Not on a purchase financed with a federally related mortgage loan. 12 U.S.C. 2608 prohibits a seller from requiring, directly or indirectly, that the buyer purchase title insurance from a particular company, and makes the seller liable for three times all charges made for the title insurance. Regulation X repeats the prohibition at 12 CFR 1024.16.
Why does the Closing Disclosure show a different owner policy amount than the title quote
Because federal title insurance disclosure rules require the lender policy to be disclosed at its full non-simultaneous premium and the owner policy at the full owner premium plus the simultaneous loan premium minus the full lender premium. The total matches the quote; only the split between the two lines changes. The CFPB published a factsheet in June 2020 that walks through the arithmetic with examples.
What does a transaction coordinator check on a title insurance commitment
Schedule A against the contract (parties, price, legal description, vesting), every Schedule B Part I requirement as a task with an owner, and every Schedule B Part II exception against the exceptions the contract already permits. In Texas the objection deadline in TREC paragraph 6D runs from receipt of the commitment, exception documents, and survey, restarts on any revision, and does not waive the requirements even if the buyer misses it.

Written by Vikas Malpani
Vikas Malpani is the CEO and Co-Founder of ReBillion and a CAR-Certified Transaction Coordinator. A serial real estate technology entrepreneur with 15+ years across technology and real estate operations, he was named to MIT Technology Review's TR35 list of young innovators. At ReBillion he leads the AI systems that deliver compliant, accurate transaction coordination for brokerages and agents across the 10 states ReBillion serves. Connect with Vikas on LinkedIn: https://www.linkedin.com/in/vikasmalpani/
View Profile